diff --git a/gamestonk_terminal/portfolio_optimization/README.md b/gamestonk_terminal/portfolio_optimization/README.md
index 6542f2476c5..3e9e44d4603 100644
--- a/gamestonk_terminal/portfolio_optimization/README.md
+++ b/gamestonk_terminal/portfolio_optimization/README.md
@@ -114,9 +114,9 @@ Returns a portfolio that is weighted based on a selected property info
These approaches are based off of the efficient frontier approach, which is meant to solve the following optimization problem.
-Minimize:
-
-Subject to: , and
+
+
+
* Where S is the covariance matrix between stocks and R is the expected returns.
* The condition that all weights add up to 1 just implies that you want to have a net long portfolio (with no margin).
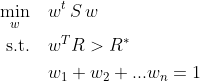 +