mirror of
https://github.com/OpenBB-finance/OpenBB.git
synced 2026-11-01 23:12:21 +00:00
Added risk indicators (#775)
* Added risk indicators

* Fixed issues

* Updated description

* Moved to QA

* Added website

* Added website

Co-authored-by: Colin Delahunty <colindelahunty@Colins-Air.indiana.edu>
This commit is contained in:
 Colin Delahunty
@@ -20,6 +20,9 @@ This menu aims to perform exploratory data analysis on a pre-loaded stock, and t
|
||||
* detects abrupt changes using cumulative sum algorithm
|
||||
* [acf](#acf)
|
||||
* (partial) auto-correlation function differentials
|
||||
* [capm](#capm)
|
||||
* capital asset pricing model
|
||||
|
||||
|
||||
|
||||
## summary <a name="summary"></a>
|
||||
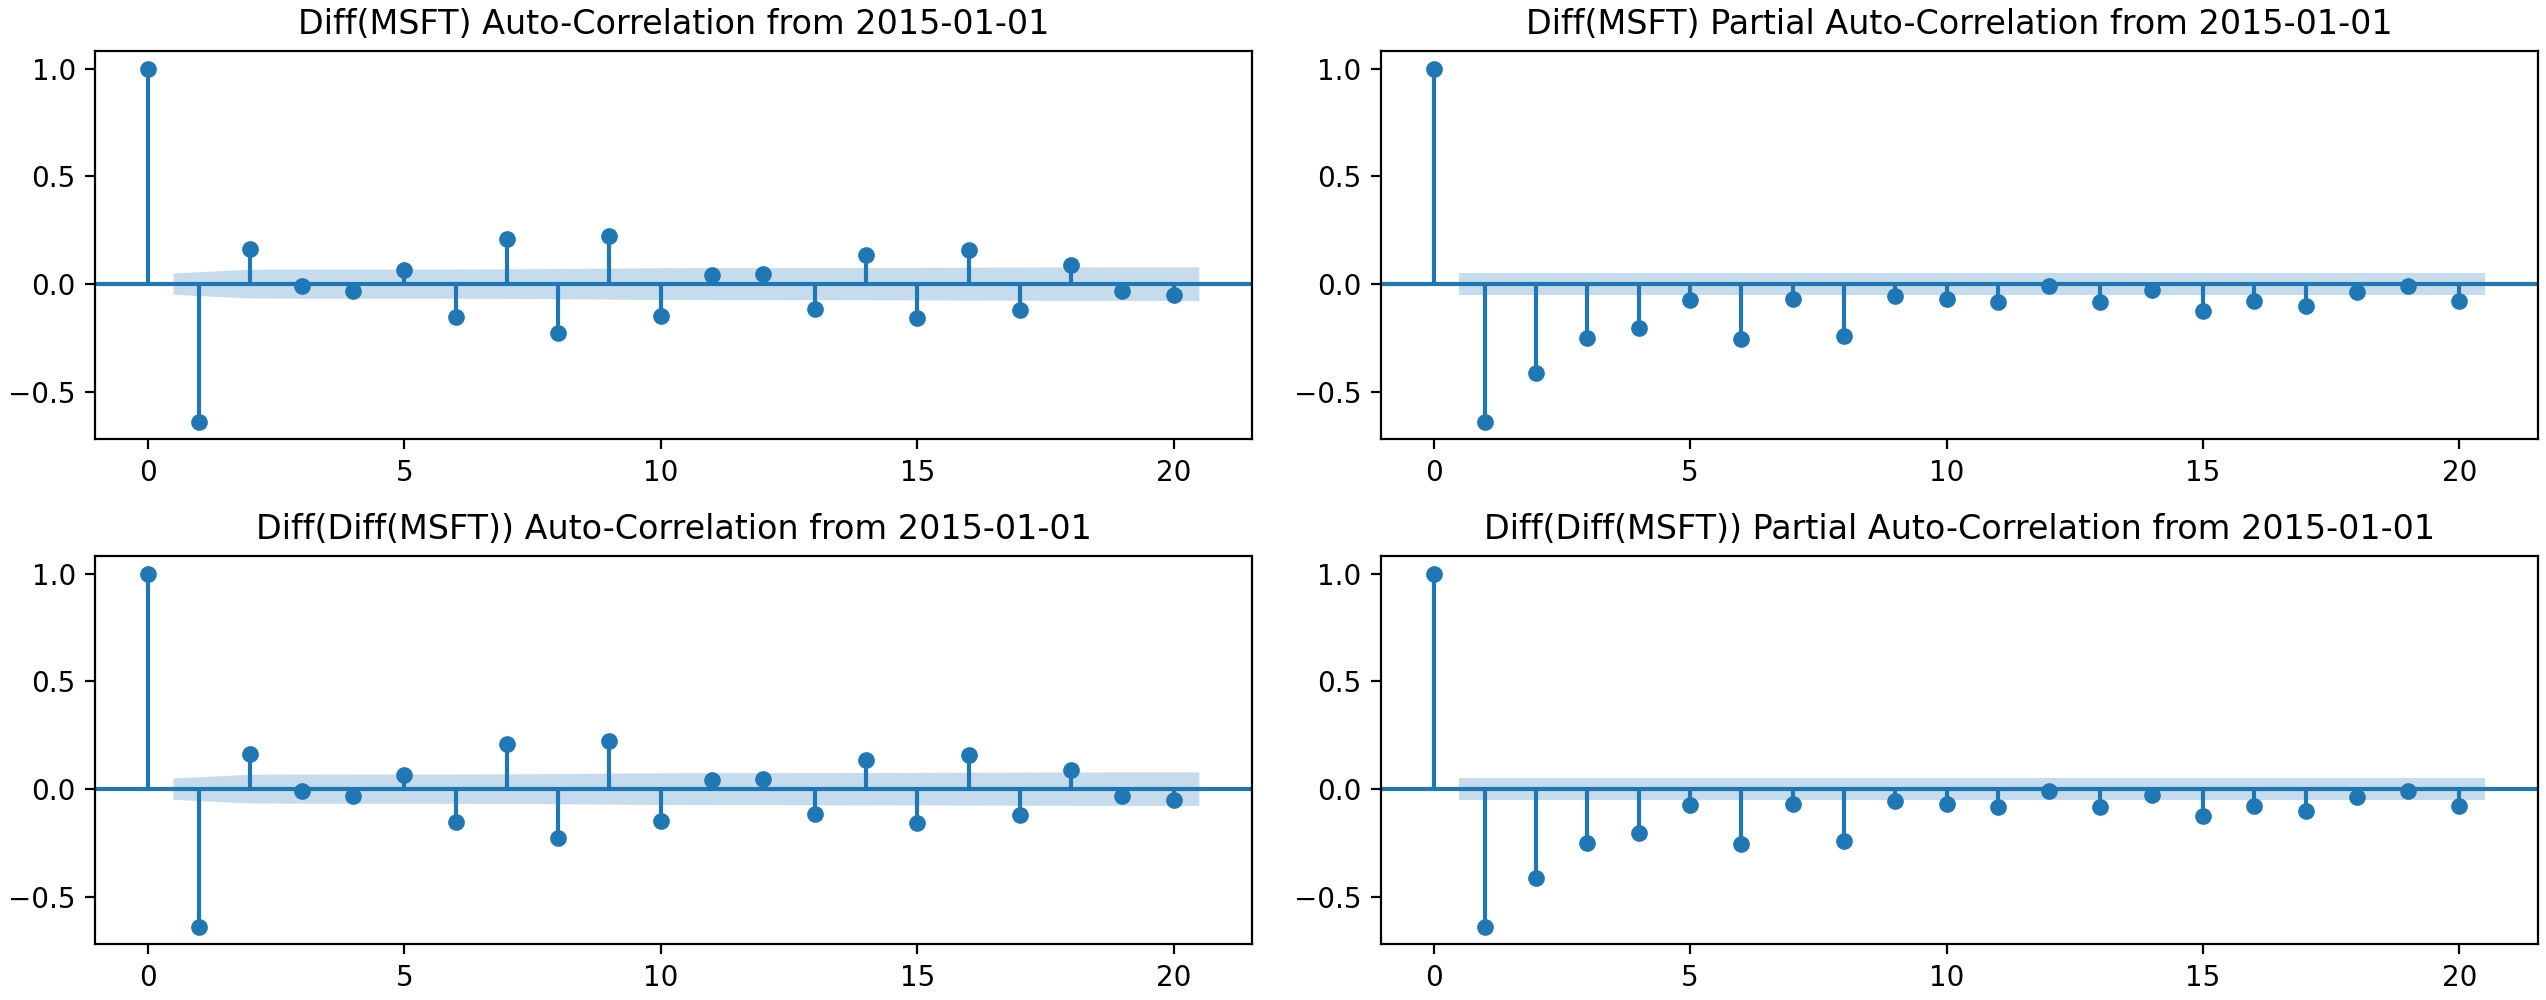
@@ -132,3 +135,15 @@ Auto-Correlation and Partial Auto-Correlation Functions for diff and diff diff s
|
||||
* -l : maximum lags to display in plots. Default 40.
|
||||
|
||||
|
||||
|
||||
|
||||
## capm <a name="capm"></a>
|
||||
|
||||
```text
|
||||
usage: capm
|
||||
```
|
||||
|
||||
Capital asset pricing model for a given stock.
|
||||
|
||||
|
||||
![capm]
|
||||
|
||||
@@ -0,0 +1,78 @@
|
||||
"""Factors model"""
|
||||
__docformat__ = "numpy"
|
||||
|
||||
from urllib.request import urlopen
|
||||
from zipfile import ZipFile
|
||||
from io import BytesIO
|
||||
|
||||
import statsmodels.api as sm
|
||||
import yfinance as yf
|
||||
import pandas as pd
|
||||
import numpy as np
|
||||
|
||||
|
||||
def get_fama_raw():
|
||||
"""Gets base Fama French data to calculate risk"""
|
||||
with urlopen(
|
||||
"http://mba.tuck.dartmouth.edu/pages/faculty/ken.french/ftp/F-F_Research_Data_Factors_CSV.zip"
|
||||
) as url:
|
||||
|
||||
# Download Zipfile and create pandas DataFrame
|
||||
with ZipFile(BytesIO(url.read())) as zipfile:
|
||||
with zipfile.open("F-F_Research_Data_Factors.CSV") as zip_open:
|
||||
df = pd.read_csv(
|
||||
zip_open,
|
||||
header=0,
|
||||
names=["Date", "MKT-RF", "SMB", "HML", "RF"],
|
||||
skiprows=3,
|
||||
)
|
||||
|
||||
df = df[df["Date"].apply(lambda x: len(str(x).strip()) == 6)]
|
||||
df["Date"] = df["Date"].astype(str) + "01"
|
||||
df["Date"] = pd.to_datetime(df["Date"], format="%Y%m%d")
|
||||
df["MKT-RF"] = pd.to_numeric(df["MKT-RF"], downcast="float")
|
||||
df["SMB"] = pd.to_numeric(df["SMB"], downcast="float")
|
||||
df["HML"] = pd.to_numeric(df["HML"], downcast="float")
|
||||
df["RF"] = pd.to_numeric(df["RF"], downcast="float")
|
||||
df["MKT-RF"] = df["MKT-RF"] / 100
|
||||
df["SMB"] = df["SMB"] / 100
|
||||
df["HML"] = df["HML"] / 100
|
||||
df["RF"] = df["RF"] / 100
|
||||
df = df.set_index("Date")
|
||||
return df
|
||||
|
||||
|
||||
def get_historical_5(ticker: str):
|
||||
"""Get 5 year monthly historical performance for a ticker with dividends filtered"""
|
||||
tick = yf.Ticker(ticker)
|
||||
df = tick.history(period="5y", interval="1mo")
|
||||
df = df[df.index.to_series().apply(lambda x: x.day == 1)]
|
||||
df = df.drop(["Dividends", "Stock Splits"], axis=1)
|
||||
df = df.dropna()
|
||||
return df
|
||||
|
||||
|
||||
def capm_information(ticker):
|
||||
"""Provides information that relates to the CAPM model"""
|
||||
df_f = get_fama_raw()
|
||||
df_h = get_historical_5(ticker)
|
||||
df = df_h.join(df_f)
|
||||
df = df.dropna()
|
||||
df["Monthly Return"] = df["Close"].pct_change()
|
||||
df["Excess Monthly Return"] = df["Monthly Return"] - df["RF"]
|
||||
df["Excess MKT-RF"] = df["MKT-RF"] - df["RF"]
|
||||
df = df.dropna()
|
||||
y = df[["Excess Monthly Return"]]
|
||||
x = df["Excess MKT-RF"]
|
||||
x = sm.add_constant(x)
|
||||
model = sm.OLS(y, x).fit()
|
||||
beta = model.params["Excess MKT-RF"]
|
||||
beta2 = beta ** 2
|
||||
m_variance = np.var(df["Excess MKT-RF"])
|
||||
syst = beta2 * m_variance
|
||||
ss = model.ssr
|
||||
deg_free = model.df_resid
|
||||
unsys = ss / deg_free
|
||||
sy = (syst / (syst + unsys)) * 100
|
||||
us = (unsys / (syst + unsys)) * 100
|
||||
return beta, m_variance, sy, us
|
||||
@@ -0,0 +1,15 @@
|
||||
"""Factors view"""
|
||||
__docformat__ = "numpy"
|
||||
|
||||
from gamestonk_terminal.stocks.quantitative_analysis.factors_model import (
|
||||
capm_information,
|
||||
)
|
||||
|
||||
|
||||
def capm_view(ticker):
|
||||
"""A view that displays information for the CAPM model."""
|
||||
beta, m_variance, sy, us = capm_information(ticker)
|
||||
print(f"Beta:\t\t\t{beta:.2f}")
|
||||
print(f"Market Variance:\t{m_variance:.4f}")
|
||||
print(f"Systematic Risk:\t{sy:.2f}%")
|
||||
print(f"Unsystematic Risk:\t{us:.2f}%\n")
|
||||
@@ -24,6 +24,7 @@ from gamestonk_terminal.helper_funcs import (
|
||||
parse_known_args_and_warn,
|
||||
)
|
||||
from gamestonk_terminal.menu import session
|
||||
from gamestonk_terminal.stocks.quantitative_analysis.factors_view import capm_view
|
||||
|
||||
|
||||
class QaController:
|
||||
@@ -49,6 +50,7 @@ class QaController:
|
||||
"unitroot",
|
||||
"goodness",
|
||||
"unitroot",
|
||||
"capm",
|
||||
]
|
||||
|
||||
CHOICES += CHOICES_COMMANDS
|
||||
@@ -116,6 +118,7 @@ Rolling Metrics:
|
||||
Other:
|
||||
decompose decomposition in cyclic-trend, season, and residuals of prices
|
||||
cusum detects abrupt changes using cumulative sum algorithm of prices
|
||||
capm capital asset pricing model
|
||||
"""
|
||||
print(help_str)
|
||||
|
||||
@@ -768,6 +771,26 @@ Other:
|
||||
except Exception as e:
|
||||
print(e, "\n")
|
||||
|
||||
def call_capm(self, other_args: List[str]):
|
||||
"""Process capm command"""
|
||||
parser = argparse.ArgumentParser(
|
||||
add_help=False,
|
||||
formatter_class=argparse.ArgumentDefaultsHelpFormatter,
|
||||
prog="capm",
|
||||
description="""
|
||||
Provides detailed information about a stock's risk compared to the market risk.
|
||||
""",
|
||||
)
|
||||
|
||||
try:
|
||||
ns_parser = parse_known_args_and_warn(parser, other_args)
|
||||
if not ns_parser:
|
||||
return
|
||||
capm_view(self.ticker)
|
||||
|
||||
except Exception as e:
|
||||
print(e, "\n")
|
||||
|
||||
|
||||
def menu(ticker: str, start: datetime, interval: str, stock: pd.DataFrame):
|
||||
"""Statistics Menu"""
|
||||
|
||||
@@ -1,6 +1,7 @@
|
||||
"""Technical Analysis Controller Module"""
|
||||
__docformat__ = "numpy"
|
||||
# pylint:disable=too-many-lines
|
||||
# pylint:disable=R0904
|
||||
|
||||
import argparse
|
||||
import os
|
||||
|
||||
12
website/content/stocks/quantitative_analysis/capm/_index.md
vendored
Normal file
12
website/content/stocks/quantitative_analysis/capm/_index.md
vendored
Normal file
@@ -0,0 +1,12 @@
|
||||
```text
|
||||
usage: capm [-h]
|
||||
```
|
||||
|
||||
Capital asset pricing model
|
||||
|
||||
```
|
||||
optional arguments:
|
||||
-h, --help show this help message (default: False)
|
||||
```
|
||||
|
||||
![capm]
|
||||
2
website/data/menu/main.yml
vendored
2
website/data/menu/main.yml
vendored
@@ -501,6 +501,8 @@ main:
|
||||
ref: "/stocks/quantitative_analysis/decompose"
|
||||
- name: cusum
|
||||
ref: "/stocks/quantitative_analysis/cusum"
|
||||
- name: capm
|
||||
ref: "/stocks/quantitative_analysis/capm"
|
||||
- name: prediction techniques
|
||||
ref: "/stocks/prediction_techniques"
|
||||
sub:
|
||||
|
||||
Reference in New Issue
Block a user