 747c53512d
* test * ultima description (#5541) * Updating showcase page (#5543) * updating showcase page * use sdk instead * add new bot command autopost docs (#5530) add new bot command autopost docs to docs.openbb.co Co-authored-by: James Maslek <jmaslek11@gmail.com> * Hotfix/ultima improvements (#5553) * tweaks for monetization * fix linting issue * fix: Modify 'load' behavior to append data to existing sheet (#5503) * fix: Modify 'load' behavior to append data to existing sheet Details: - Added logic to detect existing sheet and append data if present. - There is no direct way to append on the sheet, so I am reading the sheet to get the last row number and then writing after that row number. Resolves: #5472 * Fixed 'worksheet not found' error during export to an existing sheet * Changes: * Now if the sheet exists in the xlsx file it will ask the user if he wants to replace/append/create new sheet --------- Co-authored-by: Danglewood <85772166+deeleeramone@users.noreply.github.com> * added platform API integration test to Nightly build (#5571) * Add columns to `stocks/search` (#5565) * Add columns to `stocks/search` isin, cusip, figi, composite_figi, shareclass_figi * Update test_search[False].txt * Update test_search[True].txt * Delete tests/openbb_terminal/stocks/cassettes/test_stocks_helper/test_search.yaml * Create test_search.yaml --------- Co-authored-by: Danglewood <85772166+deeleeramone@users.noreply.github.com> * updating ultima urls (#5587) * fix: A value is trying to be set on a copy of a slice from a DataFrame #5582 (#5591) * Update README.md (#5598) * Hotfix/econometrics export filename fix (#5508) * fix: Modify 'load' behavior to append data to existing sheet Details: - Added logic to detect existing sheet and append data if present. - There is no direct way to append on the sheet, so I am reading the sheet to get the last row number and then writing after that row number. Resolves: #5472 * Added --export option for exporting to a desired file in /econometrics menu * Added a -f/--file option to provide the filename for export. Made -t/--type and -f/--file mutually exclusive. If -f is not given, -t is required and the filename will be generated based on the time and module. * Revert `helper_funcs.py` to original state * Made some arguments not required. * Minor changes asked by @deeleeramone * No sheet name * black --------- Co-authored-by: James Maslek <jmaslek11@gmail.com> Co-authored-by: Danglewood <85772166+deeleeramone@users.noreply.github.com> * FIX #5600 Updated the Twitter logo to X logo (#5601) * Change Ultima paragraph (#5624) * change ultima paragraph * remove old paragraph * Update CONTRIBUTING.md (#5623) * mobile line-brake fixed (#5604) In the mobile view (media max 400px ), the text line "Installation >>" appears broken into smaller segments. Co-authored-by: James Maslek <jmaslek11@gmail.com> * Docs/terminalpro and improvement (#5622) * add first iteration of content for Terminal Pro * Update index.md * Update dashboards.md * Update folders.md * Update grouping.md * Update report.md * Update templates.md * Update quick-start.md * Update index.md * Update index.md * Update home.md * Update news.md * Update index.md * Update index.md * Update index.md * Update data-provider.md * Update chat-with-widget.md * Update data-manipulation.md * Update forecasting.md * fix: images self closing tags * fix: only pro visitors can see pro * inter font * improve SEO content and restructuring * add new package for toggle on tutorials * move folder around * improve main page of each prod * small updates and improvements * fix logo above * small improvement in headtitle for portfolio funcs * fix typos from OpenAI's GPT-4 * fix _category_ json * remove generic SEO words * add script that generates SEO for documentation * add missing file * remove sdk warning message * fix links for andrew --------- Co-authored-by: jose-donato <zmcdonato@gmail.com> Co-authored-by: jose-donato <43375532+jose-donato@users.noreply.github.com> Co-authored-by: andrewkenreich <andrew.kenreich@gmail.com> * Add light blue banner, blue when clicking sidebar + fix link in docusaurus.config.js (#5627) * typo * pro docs tab coloring * sidebar selection blue * redirecting missing * fix docs (#5646) * Fix the redirect for intro to the correct url for docs (#5658) * fix the redirect for intro to the correct url for docs * fix code linting --------- Co-authored-by: James Maslek <jmaslek11@gmail.com> * Improve Pro documentation further (#5641) * small improvement * Fix TutorialVideo for mobile view * main page terminal pro docs * jose whelp * placeholder index file that needs to be removed * fix: fixes sidebar, removes unused index.md * update link to api keys * update api keys link * fix hyperlinks in terminal helper * fix a few more links * fix some more links * linter * black linter * improve main docs page for each product * small refactor * header to take to main page of product * run OpenAI script to generate SEO for pro content --------- Co-authored-by: jose-donato <43375532+jose-donato@users.noreply.github.com> * Update folders.md * Update integrate-your-own-backend.md * Update index.md * Update settings.md (#5665) * fix front matter (#5667) * #5633 adding comma every 1000 (#5652) * #5633 adding comma every 1000 * pylint --------- Co-authored-by: Danglewood <85772166+deeleeramone@users.noreply.github.com> * Hotfix/reports model render report sanitize inputs (#5669) * Adding more robust special character handling to create_output_path(). Addresses https://github.com/OpenBB-finance/OpenBBTerminal/issues/5299 * Running black linter on code to conform to OBB style guides. --------- Co-authored-by: James Maslek <jmaslek11@gmail.com> Co-authored-by: Danglewood <85772166+deeleeramone@users.noreply.github.com> * hotfix/fix-gov-histcont: Fix #5650 - /stocks/gov/histcont (#5676) * fix histcont * some cleanup * remove sort line * 12-31 not 12-12 * columns_keep_types * remove space in regex (#5675) * Pin openai (#5685) * Clarified stocks/ta empty recom object message (#5468) * Clarified stocks/ta empty recom object message * black * lint --------- Co-authored-by: James Maslek <jmaslek11@gmail.com> * improved market cap value extraction (#5169) * improved market cap value extraction * pylint --------- Co-authored-by: James Maslek <jmaslek11@gmail.com> * 3.2.3->3.2.4 * Changelogs * new changelog --------- Co-authored-by: Henrique Joaquim <h.joaquim@campus.fct.unl.pt> Co-authored-by: Andrew <andrew.kenreich@gmail.com> Co-authored-by: Adi Sai <adithya.sairam1@gmail.com> Co-authored-by: Sandip Saha <sandipsmoto@gmail.com> Co-authored-by: Danglewood <85772166+deeleeramone@users.noreply.github.com> Co-authored-by: Luqman <luqazino@gmail.com> Co-authored-by: Adwait <111136306+AdwaitSalankar@users.noreply.github.com> Co-authored-by: Abhishek Amar <66067391+abhishek-amar@users.noreply.github.com> Co-authored-by: DidierRLopes <dro.lopes@campus.fct.unl.pt> Co-authored-by: professssor <62937125+professssor@users.noreply.github.com> Co-authored-by: Farookh Zaheer Siddiqui <129654632+FarukhS52@users.noreply.github.com> Co-authored-by: MAX SHESTOV <57421753+maxxsh@users.noreply.github.com> Co-authored-by: jose-donato <zmcdonato@gmail.com> Co-authored-by: jose-donato <43375532+jose-donato@users.noreply.github.com> Co-authored-by: Mohamad Fadil <fadil.parves@gmail.com> Co-authored-by: Ramazan <guvencramazan@outlook.com> Co-authored-by: joshuabuildsthings <joshuabuildsthings@users.noreply.github.com> Co-authored-by: wojda <114031148+polooner@users.noreply.github.com> Co-authored-by: Bim Phomthong <118195204+bimbolimbo@users.noreply.github.com>
8.9 KiB
Vendored
title, description, keywords
| title | description | keywords | |||||||||||
|---|---|---|---|---|---|---|---|---|---|---|---|---|---|
| Quantitative Analysis | The page provides a comprehensive guide on how to use the 'qa' module of the Terminal's Quantitative Analysis menu for SDK environment. It contains detailed information about the grouping of functions into categories, examples on their usage, and how they provide users more ways to interact with the function library. |
|
import HeadTitle from '@site/src/components/General/HeadTitle.tsx';
The qa module is the Terminal's Quantitative Analysis menu for the SDK environment. It provides users with more ways to interact with the library of functions, and provides cross-disciplinary utility. To activate the code completion for the menu, enter . after, openbb.qa.
How to Use
The functions of the qa module are grouped into categories, listed below along with a short description.
| Path | Type | Description |
|---|---|---|
| openbb.qa.acf | Plot | Plots Auto and Partial Correlation of Returns and Change in Returns |
| openbb.qa.bw | Plot | Box and Whisker Plot |
| openbb.qa.calculate_adjusted_var | Risk | Calculates VaR, adjusted for skew and kurtosis (Cornish-Fisher-Expansion) |
| openbb.qa.cdf | Plot | Plots the Cumulative Distribution Function |
| openbb.qa.cusum | Plot | Plots the Cumulative Sum Algorithm |
| openbb.qa.decompose | Plot | Decomposition in Cyclic-Trend, Season & Residuals of Prices |
| openbb.qa.es | Statistics | Expected Shortfall per percentile |
| openbb.qa.kurtosis | Rolling Metrics | Rolling Kurtosis of Distribution of Prices |
| openbb.qa.line | Plot | Customizable Line Plot, With Annotations |
| openbb.qa.normality | Statistics | Normality Statistics and Tests |
| openbb.qa.omega | Risk | Omega Ratio (Risk/Return Performance Measure) |
| openbb.qa.quantile | Rolling Metrics | Rolling Median and Quantile of Prices |
| openbb.qa.qqplot | Plot | QQ Plot for Data Against Normal Quantiles |
| openbb.qa.rolling | Rolling Metrics | Rolling Mean and Standard Deviation of Prices |
| openbb.qa.sharpe | Risk | Sharpe Ratio (Measure of Risk-Adjusted Return) |
| openbb.qa.skew | Rolling Metrics | Rolling Skewness of Distribution of Prices |
| openbb.qa.sortino | Risk | Sortino Ratio Risk Adjustment Metric |
| openbb.qa.spread | Rolling Metrics | Rolling Variance and Standard Deviation of Prices |
| openbb.qa.summary | Statistics | A Brief Summary of Statistics for the DataFrame |
| openbb.qa.unitroot | Statistics | Normality Statistics and Tests |
| openbb.qa.var | Risk | Value at Risk |
Examples
Import Statements
The examples below will assume that the following statements are included in the first block of code:
import quandl
import pandas as pd
from openbb_terminal.sdk import openbb
from openbb_terminal import config_terminal as cfg

# %matplotlib inline (uncomment if using a Jupyter environment)
Get Data
This example collects data from Nasdaq Data Link, and requires registering for a free API key. Qunadl is the Python client for the Nasdaq Data Link API.
shiller_pe_rdiff = quandl.get('MULTPL/SHILLER_PE_RATIO_MONTH', collapse = 'monthly', transform = 'rdiff', api_key = cfg.API_KEY_QUANDL)
shiller_pe_rdiff.rename(columns={'Value':'P/E % Change'}, inplace = True)
shiller_pe_ratio = quandl.get('MULTPL/SHILLER_PE_RATIO_MONTH', collapse = 'monthly', api_key = cfg.API_KEY_QUANDL)
shiller_pe_ratio.rename(columns={'Value':'P/E Ratio'}, inplace = True)

sp500_inf_adj = quandl.get('MULTPL/SP500_INFLADJ_MONTH', collapse = 'monthly', api_key = cfg.API_KEY_QUANDL)
sp500_inf_adj.rename(columns = {'Value': 'S&P Inflation-Adjusted Value'}, inplace = True)
sp500_inf_adj_rdiff = quandl.get('MULTPL/SP500_INFLADJ_MONTH', collapse = 'monthly', transform = 'rdiff', api_key = cfg.API_KEY_QUANDL)
sp500_inf_adj_rdiff.rename(columns = {'Value':'S&P 500 % Change'}, inplace = True)

shiller_pe = shiller_pe_ratio.join(shiller_pe_rdiff)
sp500_inf_adj = sp500_inf_adj.join(sp500_inf_adj_rdiff)

sp500_df = sp500_inf_adj.join(shiller_pe)

sp500_df
| Date | S&P Inflation-Adjusted Value | S&P 500 % Change | P/E Ratio | P/E % Change |
|---|---|---|---|---|
| 2022-08-31 00:00:00 | 3955 | 0.0092504 | 29.64 | 0.022069 |
| 2022-09-30 00:00:00 | 3585.62 | -0.0933957 | 26.84 | -0.0944669 |
| 2022-10-31 00:00:00 | 3871.98 | 0.0798635 | 28.53 | 0.0629657 |
| 2022-11-30 00:00:00 | 3856.1 | -0.00410126 | 28.37 | -0.00560813 |
This particular data series contains 150 years of monthly values. It is among the longest uninterrupted timeseries available in the public domain, and it is cited frequently in macroeconomic research.
Summary
Get a summary of statistics for each column with qa.summary:
openbb.qa.summary(sp500_df)
| S&P Inflation-Adjusted Value | S&P 500 % Change | P/E Ratio | P/E % Change | |
|---|---|---|---|---|
| count | 1823 | 1822 | 1822 | 1821 |
| mean | 697.396 | 0.0028703 | 16.9914 | 0.00137084 |
| std | 834.501 | 0.0424378 | 7.07094 | 0.0412196 |
| min | 80.31 | -0.264738 | 4.78 | -0.268992 |
| 10% | 152.404 | -0.0447494 | 9.31 | -0.0449735 |
| 25% | 203.47 | -0.0172803 | 11.7 | -0.0183028 |
| 50% | 309.83 | 0.00553122 | 15.895 | 0.00446999 |
| 75% | 778.42 | 0.0260009 | 20.5575 | 0.0246575 |
| 90% | 1907.87 | 0.04505 | 26.467 | 0.0426357 |
| max | 4786.79 | 0.514085 | 44.19 | 0.511986 |
| var | 696392 | 0.00180097 | 49.9982 | 0.00169906 |
Spread
Add the variance and standard deviation, over a specified window (three-months), to the DataFrame:
std,variance = openbb.qa.spread(data = sp500_df['S&P 500 % Change'], window = 3)
std.rename(columns = {'STDEV_3':'Three-Month Standard Deviation'}, inplace = True)
variance.rename(columns = {'VAR_3': 'Three-Month Variance'}, inplace =True)
sp500_df = sp500_df.join([std,variance])
sp500_df.rename_axis('date', inplace = True)
sp500_df.tail(2)
| date | S&P Inflation-Adjusted Value | S&P 500 % Change | P/E Ratio | P/E % Change | Three-Month Standard Deviation | Three-Month Variance |
|---|---|---|---|---|---|---|
| 2022-10-31 00:00:00 | 3871.98 | 0.0798635 | 28.53 | 0.0629657 | 0.0871217 | 0.00759019 |
| 2022-11-30 00:00:00 | 3856.1 | -0.00410126 | 28.37 | -0.00560813 | 0.0866432 | 0.00750705 |
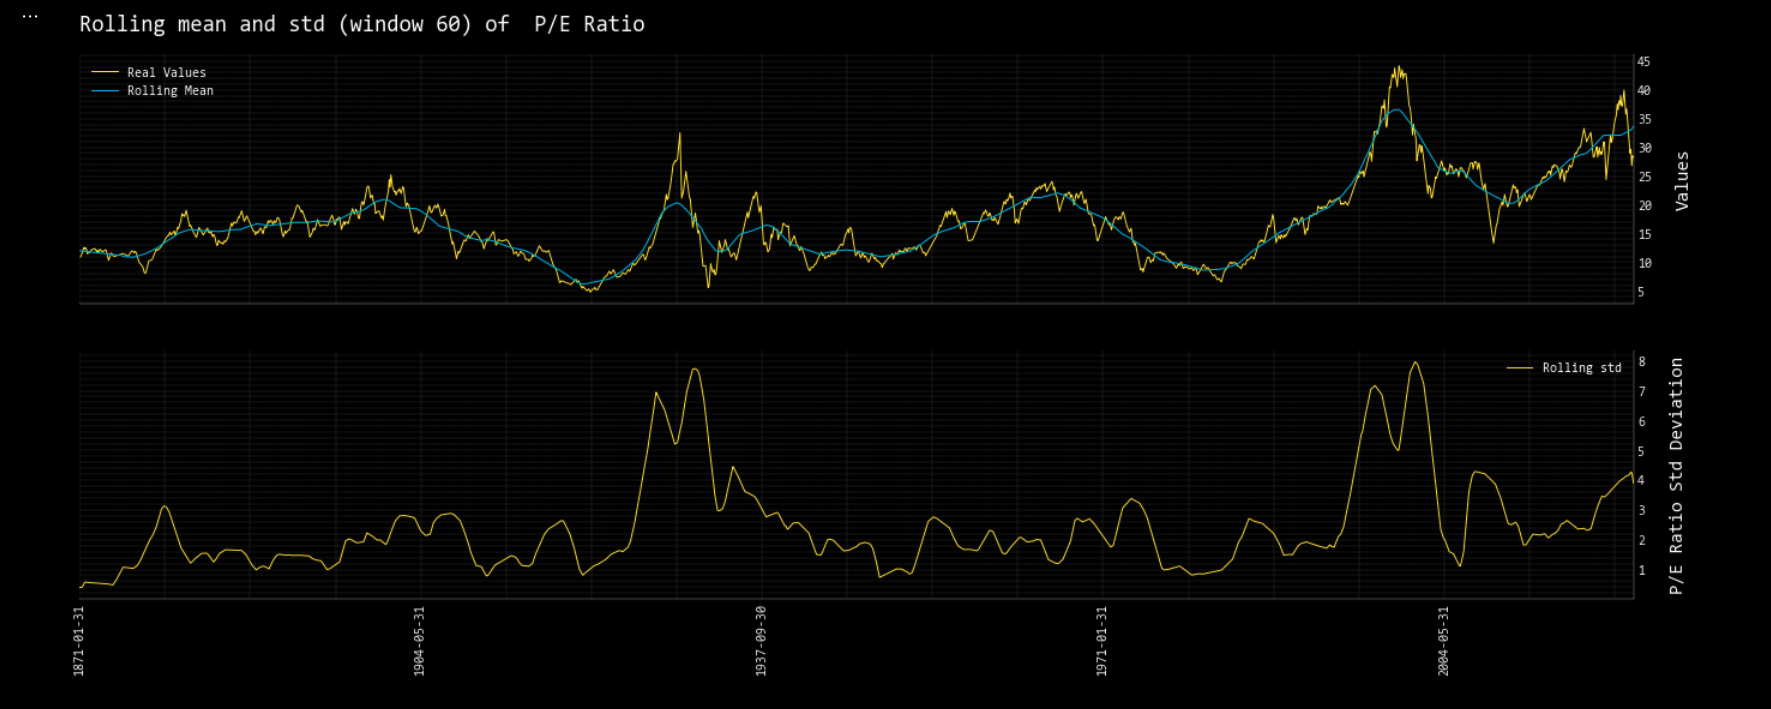
The rolling mean average and standard deviation is calculated with the rolling command. Adding, _chart, to this will return an inline chart within a Jupyter Notebook. For the example below, window, 60, represents a five-year period.
Rolling
openbb.qa.rolling_chart(sp500_df, target = 'P/E Ratio', window = 60, symbol = '')
Unit Root Test
Perform a unit root test with unitroot:
help(openbb.qa.unitroot)

        Parameters
        ----------
        data : pd.DataFrame
            DataFrame of target variable
        fuller_reg : str
            Type of regression of ADF test. Can be ‘c’,’ct’,’ctt’,’nc’ 'c' - Constant and t - trend order
        kpss_reg : str
            Type of regression for KPSS test.  Can be ‘c’,’ct'

        Returns
        -------
        pd.DataFrame
            Dataframe with results of ADF test and KPSS test

openbb.qa.unitroot(sp500_df['P/E % Change'])
| ADF | KPSS | |
|---|---|---|
| Test Statistic | -10.7075 | 0.34061374135067696 |
| P-Value | 3.3972e-19 | 0.1 |
| NLags | 20 | 2 |
| Nobs | 1800 | |
| ICBest | -6491.14 |