mirror of
https://github.com/OpenBB-finance/OpenBB.git
synced 2026-11-03 16:02:04 +00:00
 4ad995fdd0
* add first iteration of content for Terminal Pro

* Update index.md

* Update dashboards.md

* Update folders.md

* Update grouping.md

* Update report.md

* Update templates.md

* Update quick-start.md

* Update index.md

* Update index.md

* Update home.md

* Update news.md

* Update index.md

* Update index.md

* Update index.md

* Update data-provider.md

* Update chat-with-widget.md

* Update data-manipulation.md

* Update forecasting.md

* fix: images self closing tags

* fix: only pro visitors can see pro

* inter font

* improve SEO content and restructuring

* add new package for toggle on tutorials

* move folder around

* improve main page of each prod

* small updates and improvements

* fix logo above

* small improvement in headtitle for portfolio funcs

* fix typos from OpenAI's GPT-4

* fix _category_ json

* remove generic SEO words

* add script that generates SEO for documentation

* add missing file

* remove sdk warning message

* fix links for andrew

---------

Co-authored-by: jose-donato <zmcdonato@gmail.com>
Co-authored-by: jose-donato <43375532+jose-donato@users.noreply.github.com>
Co-authored-by: andrewkenreich <andrew.kenreich@gmail.com>
562 lines
26 KiB
Markdown
Vendored
562 lines
26 KiB
Markdown
Vendored
---
|
|
title: Options Chains
|
|
description: A technical guide detailing how to load options chains data from six
|
|
different sources into memory using openbb. Reviews how to properly filter, sort,
|
|
and analyze this kind of data, and outlines the process for implementing various
|
|
options strategies. This document is heavily focused on technical processes within
|
|
a financial context.
|
|
keywords:
|
|
- Options Chains Data
|
|
- Option Strategies
|
|
- Financial Data
|
|
- Data Filtering
|
|
- Data Sorting
|
|
- Data Visualization
|
|
---
|
|
|
|
import HeadTitle from '@site/src/components/General/HeadTitle.tsx';
|
|
|
|
<HeadTitle title="Options Chains - Stocks - Intros - Usage | OpenBB SDK Docs" />
|
|
|
|
## Overview
|
|
|
|
### Options Data Object
|
|
|
|
Options chains data is loaded to memory by using the function, `openbb.stocks.options.load_options_chains()`, and is available from six sources:
|
|
|
|
- CBOE
|
|
- Intrinio (no free data)
|
|
- Nasdaq
|
|
- TMX
|
|
- Tradier (requires Sandbox developer key)
|
|
- YahooFinance
|
|
|
|
Every source will return the same object which has data and additional callable functions bound to the class. They are methods for filtering, sorting, and analyzing the data contained within.
|
|
|
|
```python
|
|
from openbb_terminal.sdk import openbb
|
|
openbb.stocks.options.load_options_chains?
|
|
```
|
|
|
|
```python
|
|
Parameters
|
|
----------
|
|
symbol: str
|
|
The ticker symbol to load the data for.
|
|
source: str
|
|
The source for the data. Defaults to "CBOE". ["CBOE", "Intrinio", "Nasdaq", "TMX", "Tradier", "YahooFinance"]
|
|
date: str
|
|
The date for EOD chains data. Only available for "Intrinio" and "TMX".
|
|
pydantic: bool
|
|
Whether to return as a Pydantic Model or as a Pandas object. Defaults to False.
|
|
|
|
Returns
|
|
------
|
|
OptionsChains
|
|
chains: pd.DataFrame
|
|
The complete options chain for the ticker. Returns as a dictionary if pydantic is True.
|
|
expirations: list[str]
|
|
List of unique expiration dates. (YYYY-MM-DD)
|
|
strikes: list[float]
|
|
List of unique strike prices.
|
|
last_price: float
|
|
The last price of the underlying asset.
|
|
underlying_name: str
|
|
The name of the underlying asset.
|
|
underlying_price: pd.Series
|
|
The price and recent performance of the underlying asset. Returns as a dictionary if pydantic is True.
|
|
hasIV: bool
|
|
Returns implied volatility.
|
|
hasGreeks: bool
|
|
Returns greeks data.
|
|
symbol: str
|
|
The symbol entered by the user.
|
|
source: str
|
|
The source of the data.
|
|
date: str
|
|
The date, when the chains data is historical EOD.
|
|
SYMBOLS: pd.DataFrame
|
|
The symbol directory for the source, when available. Returns as a dictionary if pydantic is True.
|
|
|
|
Methods
|
|
------
|
|
chart_skew: Callable
|
|
Function to chart the implied volatility skew.
|
|
chart_stats: Callable
|
|
Function to chart a variety of volume and open interest statistics.
|
|
chart_surface: Callable
|
|
Function to chart the volatility as a 3-D surface.
|
|
chart_volatility: Callable
|
|
Function to chart the implied volatility smile.
|
|
get_skew: Callable
|
|
Function to calculate horizontal and vertical skewness.
|
|
get_stats: Callable
|
|
Function to return a table of summary statistics, by strike or by expiration.
|
|
get_straddle: Callable
|
|
Function to calculate straddles and the payoff profile.
|
|
get_strangle: Callable
|
|
Function to calculate strangles and the payoff profile.
|
|
get_synthetic_long: Callable
|
|
Function to calculate a synthetic long position.
|
|
get_synthetic_short: Callable
|
|
Function to calculate a synthetic short position.
|
|
get_vertical_call_spread: Callable
|
|
Function to calculate vertical call spreads.
|
|
get_vertical_put_spreads: Callable
|
|
Function to calculate vertical put spreads.
|
|
get_strategies: Callable
|
|
Function for calculating multiple straddles and strangles at different expirations and moneyness.
|
|
```
|
|
|
|
## Loading Data
|
|
|
|
### `load_options_chains()`
|
|
|
|
The default source to load data from is, `CBOE`. Use the command below to get started.
|
|
|
|
```python
|
|
from openbb_terminal.sdk import openbb
|
|
spy = openbb.stocks.options.load_options_chains("SPY")
|
|
```
|
|
|
|
The result is returned as the object described in the previous section.
|
|
|
|
|
|
|
|
The object is still returned if an unsupported symbol is requested and a message will be printed.
|
|
|
|
```python
|
|
In [4]: data = openbb.stocks.options.load_options_chains("spyyy")
|
|
The symbol, SPYYY, was not found in the CBOE directory.
|
|
|
|
In [5]: data.chains
|
|
Out[5]: pandas.core.frame.DataFrame
|
|
```
|
|
|
|
Where available, symbols are verified against a source-specific symbol directory. This is accessible from the Options data object as the attribute named, `SYMBOLS`.
|
|
|
|
```python
|
|
data.SYMBOLS.filter(like = "SPY", axis = 0)
|
|
```
|
|
|
|
| Symbol | Company Name | DPM Name | Post/Station |
|
|
|:---------|:-------------------------------|:-------------------------|:---------------|
|
|
| SPY | SPDR S&P 500 ETF TR TR UNIT | Morgan Stanley & Co. LLC | 8/1 |
|
|
| SPYG | SPDR SER TR PRTFLO S&P500 GW | Belvedere Trading LLC | 6/1 |
|
|
| SPYD | SPDR SER TR PRTFLO S&P500 HI | Citadel Securities LLC | 6/1 |
|
|
| SPYV | SPDR SER TR PRTFLO S&P500 VL | Belvedere Trading LLC | 6/1 |
|
|
| NSPY | UNIFIED SER TR NIGHTSHARES 500 | Wolverine Trading, LLC | 3/1 |
|
|
|
|
:::note
|
|
A valid symbol will not always have listed options.
|
|
:::
|
|
|
|
Key information for the underlying asset are stored in the object as `last_price`, `underlying_name`, and `underlying_price`. The information returned to `underlying_price` will vary by source, but all column headers and index names related to the raw data are formatted in camelCase.
|
|
|
|
CBOE:
|
|
|
|
```python
|
|
In [7]: data.underlying_price
|
|
Out[7]:
|
|
type stock
|
|
tick down
|
|
bid 449.18
|
|
bidSize 1
|
|
askSize 5
|
|
ask 449.2
|
|
price 449.28
|
|
open 450.56
|
|
high 451.36
|
|
low 448.49
|
|
close 449.28
|
|
volume 69772484
|
|
previousClose 449.28
|
|
change -0.28
|
|
changePercent -0.0623
|
|
ivThirty 10.947
|
|
ivThirtyChange 0.0
|
|
lastTradeTimestamp 2023-07-14T16:00:00
|
|
ivThirtyOneYearHigh 30.646999
|
|
hvThirtyOneYearHigh 30.648199
|
|
ivThirtyOneYearLow 10.692
|
|
hvThirtyOneYearLow 10.0721
|
|
ivSixtyOneYearHigh 28.674999
|
|
hvSixtyOneYearHigh 29.5842
|
|
ivSixtyOneYearLow 11.245
|
|
hvsixtyOneYearLow 11.833
|
|
ivNinetyOneYearHigh 27.862
|
|
hvNinetyOneYearHigh 26.808901
|
|
ivNinetyOneYearLow 11.827
|
|
hvNinetyOneYearLow 13.3855
|
|
Name: SPY, dtype: object
|
|
```
|
|
|
|
TMX:
|
|
|
|
```python
|
|
In [8]: data = openbb.stocks.options.load_options_chains("XIU", "TMX")
|
|
|
|
In [9]: data.underlying_price
|
|
Out[9]:
|
|
time 15:59:56.910
|
|
previousClose 30.86
|
|
transactions 393
|
|
volume 50751
|
|
value 1567628
|
|
valueCAD 1567628
|
|
open 30.97
|
|
price 30.85
|
|
change -0.01
|
|
changePercent -0.03
|
|
tick 0.01
|
|
low 30.835
|
|
high 30.97
|
|
vwap 30.89
|
|
fiftyTwoWeekHigh 31.86
|
|
fiftyTwoWeekLow 27.375
|
|
Name: XIU, dtype: object
|
|
```
|
|
|
|
Not every source will return implied volatility or Greeks data. The two object attributes, `hasGreeks` and `hasIV`, act as validators for downstream functions.
|
|
|
|
```python
|
|
In [10]: data.hasIV
|
|
Out[10]: False
|
|
|
|
In [11]: data.get_skew()
|
|
Options data object does not have Implied Volatility and is required for this function.
|
|
```
|
|
|
|
#### Historical EOD Chains
|
|
|
|
Historical EOD chains data is currently available from `Intrinio` or `TMX`. The amount of historical data will depend on the subscription status with `Intrinio`, but is available from the beginning of 2009 from `TMX`. Add the `date` argument when loading the data. The price data of the underlying asset will reflect the closing price on the date entered.
|
|
|
|
```python
|
|
In [12]: data = openbb.stocks.options.load_options_chains("CCO", "TMX", date = "2016-06-29")
|
|
|
|
In [13]: data.underlying_price
|
|
Out[13]:
|
|
date 2016-06-29
|
|
bid 13.99
|
|
ask 14.01
|
|
bidSize 29
|
|
askSize 20
|
|
price 14.0
|
|
volume 801176
|
|
previousClose 13.73
|
|
change 0.27
|
|
open 13.88
|
|
high 14.09
|
|
low 13.8
|
|
valueCAD 11198995
|
|
transactions 3283
|
|
symbol CCO
|
|
Name: Cameco Corporation, dtype: object
|
|
```
|
|
|
|
## Additional Class Methods
|
|
|
|
The class methods work with the Options data object to query the loaded chains data in different ways. Column headers at this stage are cleaned and presentable for view. There are two types of operations, `get` and `chart`, with the latter being a subset of the former. The docstring (`data?` - and as shown in a section above) lists them all, as Methods, with a short description. The nuances of the functions are explained within the docstrings of each. Variations to the combinations of parameters will yield over thirty unique charts and provide nearly infinite ways to query to data stored in the object.
|
|
|
|
:::note
|
|
|
|
All `chart_` methods have boolean arguments for `raw` and `external_axes`. These return an interactive table in the PyWry window or the Plotly figure object, respectively. In a Jupyter Notebook, they will be displayed inline.
|
|
|
|
Returning the command to a variable provides the ability to style and customize charts as desired.
|
|
|
|
```python
|
|
fig = data.chart_volatility(expirations=data.expirations[1], external_axes = True)
|
|
```
|
|
|
|
:::
|
|
|
|
### `get_stats()`
|
|
|
|
```python
|
|
Parameters
|
|
----------
|
|
by: str
|
|
Whether to calculate by strike or expiration. Default is expiration.
|
|
query: DataFrame
|
|
Entry point to perform DataFrame operations on self.chains at the input stage.
|
|
|
|
Returns
|
|
-------
|
|
pd.DataFrame
|
|
Pandas DataFrame with the calculated statistics.
|
|
```
|
|
|
|
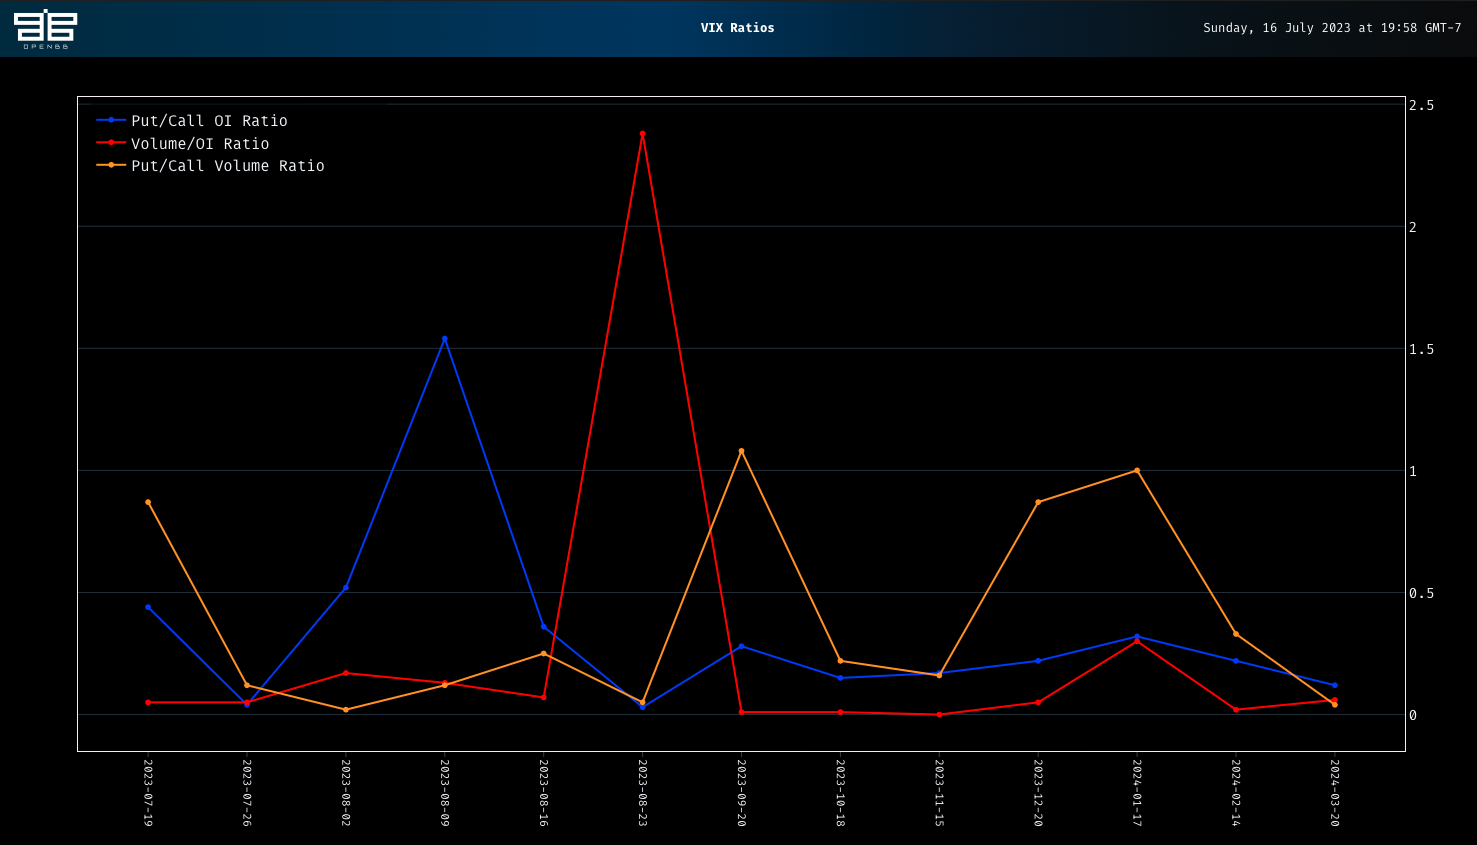
Ratios are defined as Put/Call.
|
|
|
|
```python
|
|
data = openbb.stocks.options.load_options_chains("VIX")
|
|
data.get_stats().iloc[1]
|
|
```
|
|
|
|
| | 2023-07-26 |
|
|
|:-------------|-------------:|
|
|
| Puts OI | 2018 |
|
|
| Calls OI | 45875 |
|
|
| Total OI | 47893 |
|
|
| OI Ratio | 0.04 |
|
|
| Puts OTM | 873 |
|
|
| Calls OTM | 45747 |
|
|
| Puts ITM | 1145 |
|
|
| Calls ITM | 128 |
|
|
| OTM Ratio | 0.02 |
|
|
| ITM Percent | 2.66 |
|
|
| Puts Volume | 264 |
|
|
| Calls Volume | 2156 |
|
|
| Total Volume | 2420 |
|
|
| Volume Ratio | 0.12 |
|
|
| Vol-OI Ratio | 0.05 |
|
|
|
|
The `query` parameter provides an entry point for DataFrame operations to take place prior to calculating. For example, filtering for only the options which traded during the last session.
|
|
|
|
```python
|
|
data.get_stats(query = data.chains[vix.chains["lastTradeTimestamp"] > "2023-07-14"])
|
|
```
|
|
|
|
| Expiration | Puts OI | Calls OI | Total OI | OI Ratio | Puts Volume | Calls Volume | Total Volume | Volume Ratio | Vol-OI Ratio |
|
|
|:-------------|-----------------:|-----------------:|-----------------:|-----------:|--------------:|---------------:|---------------:|---------------:|---------------:|
|
|
| 2023-07-19 | 1569778 | 3323396 | 4893174 | 0.47 | 113460 | 130416 | 243876 | 0.87 | 0.05 |
|
|
| 2023-07-26 | 1855 | 29273 | 31128 | 0.06 | 264 | 2156 | 2420 | 0.12 | 0.08 |
|
|
| 2023-08-02 | 1154 | 2498 | 3652 | 0.46 | 12 | 786 | 798 | 0.02 | 0.22 |
|
|
| 2023-08-09 | 330 | 961 | 1291 | 0.34 | 43 | 354 | 397 | 0.12 | 0.31 |
|
|
| 2023-08-16 | 907980 | 2246707 | 3154687 | 0.4 | 48668 | 197148 | 245816 | 0.25 | 0.08 |
|
|
| 2023-08-23 | 0 | 49 | 49 | 0 | 7 | 145 | 152 | 0.05 | 3.1 |
|
|
| 2023-09-20 | 614369 | 2097742 | 2712111 | 0.29 | 20750 | 19260 | 40010 | 1.08 | 0.01 |
|
|
| 2023-10-18 | 165239 | 1099858 | 1265097 | 0.15 | 3304 | 14912 | 18216 | 0.22 | 0.01 |
|
|
| 2023-11-15 | 70142 | 742698 | 812840 | 0.09 | 82 | 514 | 596 | 0.16 | 0 |
|
|
| 2023-12-20 | 44580 | 259815 | 304395 | 0.17 | 10797 | 12471 | 23268 | 0.87 | 0.08 |
|
|
| 2024-01-17 | 20860 | 43733 | 64593 | 0.48 | 23574 | 23690 | 47264 | 1 | 0.73 |
|
|
| 2024-02-14 | 1347 | 6567 | 7914 | 0.21 | 67 | 203 | 270 | 0.33 | 0.03 |
|
|
| 2024-03-20 | 63 | 1861 | 1924 | 0.03 | 8 | 219 | 227 | 0.04 | 0.12 |
|
|
|
|
### chart_stats()
|
|
|
|
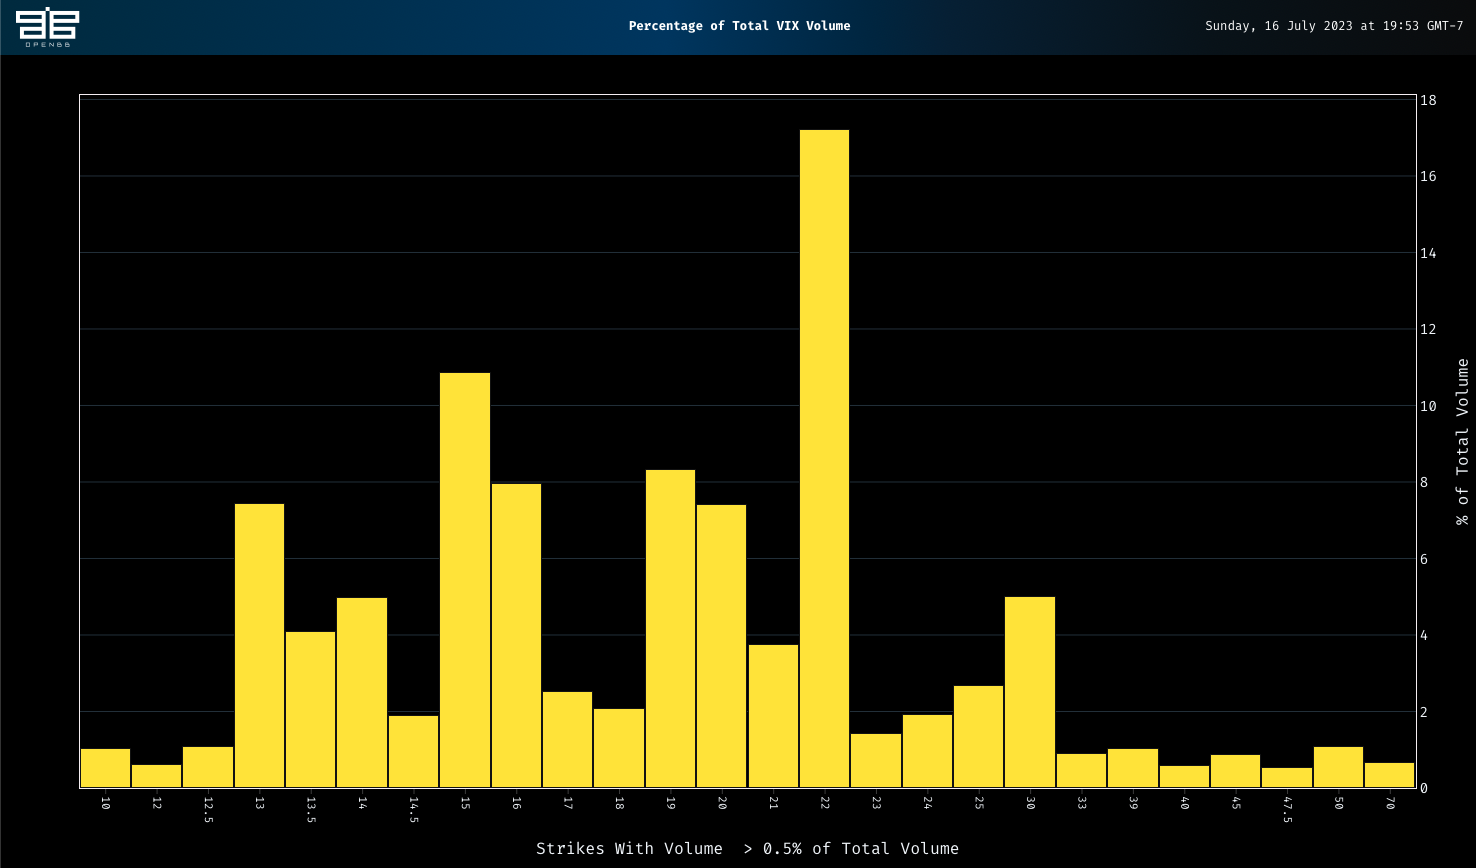
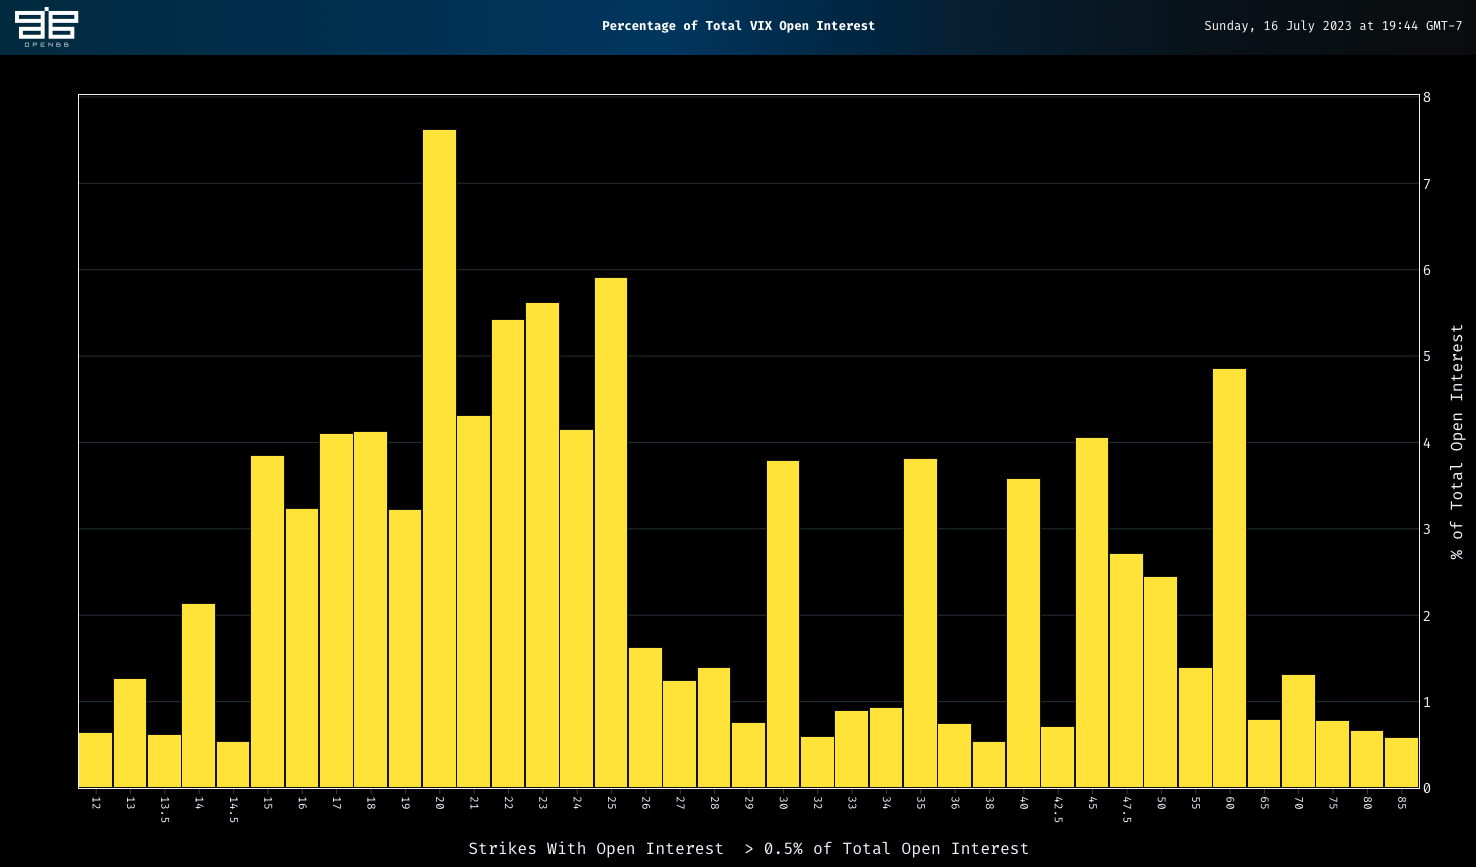
The volume and open interest metrics can be visualized in a number of ways. In general, they are bucketed as volume and open interest by strike or expiration.
|
|
|
|
```python
|
|
data.chart_stats()
|
|
```
|
|
|
|
|
|
|
|
```python
|
|
data.chart_stats(by="strike", oi=True)
|
|
```
|
|
|
|
|
|
|
|
```python
|
|
data.chart_stats(by="strike", oi=True, percent=False)
|
|
```
|
|
|
|

|
|
|
|
```python
|
|
data.chart_stats(ratios=True)
|
|
```
|
|
|
|
|
|
|
|
### Options Strategies
|
|
|
|
These methods calculate common, single-leg, strategies and return one result. The target expiry date is expressed as the number of days until expiration, and the closest expiry to supplied value will be returned. There are six types of strategies currently supported:
|
|
|
|
- `get_straddle()`
|
|
- `get_strangle()`
|
|
- `get_synthetic_long()`
|
|
- `get_synthetic_short()`
|
|
- `get_vertical_call_spread()`
|
|
- `get_vertical_put_spread()`
|
|
|
|
:::note
|
|
|
|
Looking for a place to get started as a contributor, and enjoy trading options? Strategies are an excellent starting point!
|
|
|
|
:::
|
|
|
|
All strategies share a common default setting, `days=30`. Vertical spreads require two strike prices, and they are entered as `sold`, `bought`. A bull call or put spread is entered with a bought price lower than the sold price.
|
|
|
|
```python
|
|
data.get_vertical_call_spread(30,13,12.50)
|
|
```
|
|
|
|
| | Bull Call Spread |
|
|
|:------------------------|:-------------------|
|
|
| Symbol | VIX |
|
|
| Underlying Price | 13.34 |
|
|
| Expiration | 2023-08-16 |
|
|
| DTE | 31 |
|
|
| Strike 1 | 13.0 |
|
|
| Strike 2 | 12.5 |
|
|
| Strike 1 Premium | 2.9 |
|
|
| Strike 2 Premium | 3.4 |
|
|
| Cost | 0.5 |
|
|
| Cost Percent | 3.7481 |
|
|
| Breakeven Lower | 13.0 |
|
|
| Breakeven Lower Percent | -2.5487 |
|
|
| Breakeven Upper | nan |
|
|
| Breakeven Upper Percent | nan |
|
|
| Max Profit | 0.0 |
|
|
| Max Loss | -0.5 |
|
|
| Payoff Ratio | 0.0 |
|
|
|
|
```python
|
|
data.get_vertical_put_spread(30,13,12.5)
|
|
```
|
|
|
|
| | Bull Put Spread |
|
|
|:------------------------|:---------------------|
|
|
| Symbol | VIX |
|
|
| Underlying Price | 13.34 |
|
|
| Expiration | 2023-08-16 |
|
|
| DTE | 31 |
|
|
| Strike 1 | 13.0 |
|
|
| Strike 2 | 12.5 |
|
|
| Strike 1 Premium | -0.17 |
|
|
| Strike 2 Premium | 0.12 |
|
|
| Cost | -0.05 |
|
|
| Cost Percent | 0.3748 |
|
|
| Breakeven Lower | nan |
|
|
| Breakeven Lower Percent | nan |
|
|
| Breakeven Upper | 12.95 |
|
|
| Breakeven Upper Percent | 2.92 |
|
|
| Max Profit | 0.05 |
|
|
| Max Loss | -0.45 |
|
|
| Payoff Ratio | 0.1111 |
|
|
|
|
#### `get_strategies()`
|
|
|
|
This takes all of the individual strategies and combines them into a single endpoint that can iterate over all expiry dates.
|
|
|
|
```python
|
|
data.get_strategies(days = 30, straddle_strike = data.last_price, strangle_moneyness = 30, vertical_calls = [20,15], vertical_puts = [12,15], synthetic_longs = 16, synthetic_shrots = 14)
|
|
```
|
|
|
|
| | 2023-08-16 | 2023-08-16 | 2023-08-16 | 2023-08-16 | 2023-08-16 | 2023-08-16 |
|
|
|:------------------------|:--------------------|:------------------|:---------------|:----------------|:-----------------|:-------------------|
|
|
| DTE | 31 | 31 | 31 | 31 | 31 | 31 |
|
|
| Strategy | Long Straddle | Long Strangle | Synthetic Long | Synthetic Short | Bull Call Spread | Bear Put Spread |
|
|
| Underlying Price | 13.34 | 13.34 | 13.34 | 13.34 | 13.34 | 13.34 |
|
|
| Strike 1 | 13.5 | 17.0 | 14.0 | 16.0 | 20.0 | 12.0 |
|
|
| Strike 2 | 13.5 | 10.0 | 14.0 | 16.0 | 15.0 | 15.0 |
|
|
| Strike 1 Premium | 2.62 | 1.28 | 2.31 | -1.46 | -0.83 | -0.04 |
|
|
| Strike 2 Premium | 0.33 | 0.01 | -0.49 | 1.74 | 1.83 | 1.04 |
|
|
| Cost | 2.95 | 1.29 | 1.82 | 0.28 | 1.0 | 1.0 |
|
|
| Cost Percent | 22.1139 | 9.6702 | 13.6432 | 2.099 | 7.4963 | 7.4963 |
|
|
| Breakeven Upper | 16.45 | 18.29 | 15.82 | nan | nan | nan |
|
|
| Breakeven Upper Percent | 23.3133 | 37.1064 | 18.5907 | nan | nan | nan |
|
|
| Breakeven Lower | 10.55 | 8.71 | nan | 15.72 | 16.0 | 14.0 |
|
|
| Breakeven Lower Percent | -20.9145 | -34.7076 | nan | 17.8411 | 19.94 | 17.5412 |
|
|
| Max Profit | inf | inf | inf | 15.72 | 4.0 | 2.0 |
|
|
| Max Loss | -2.95 | -1.29 | -15.82 | inf | -1.0 | -1.0 |
|
|
| Payoff Ratio | inf | inf | nan | nan | 4.0 | 2.0 |
|
|
|
|
The default state of `get_strategies()` is to return all ATM straddles. This information can be useful for charting the term structure and expected move of the underlying asset.
|
|
|
|
### Volatility
|
|
|
|
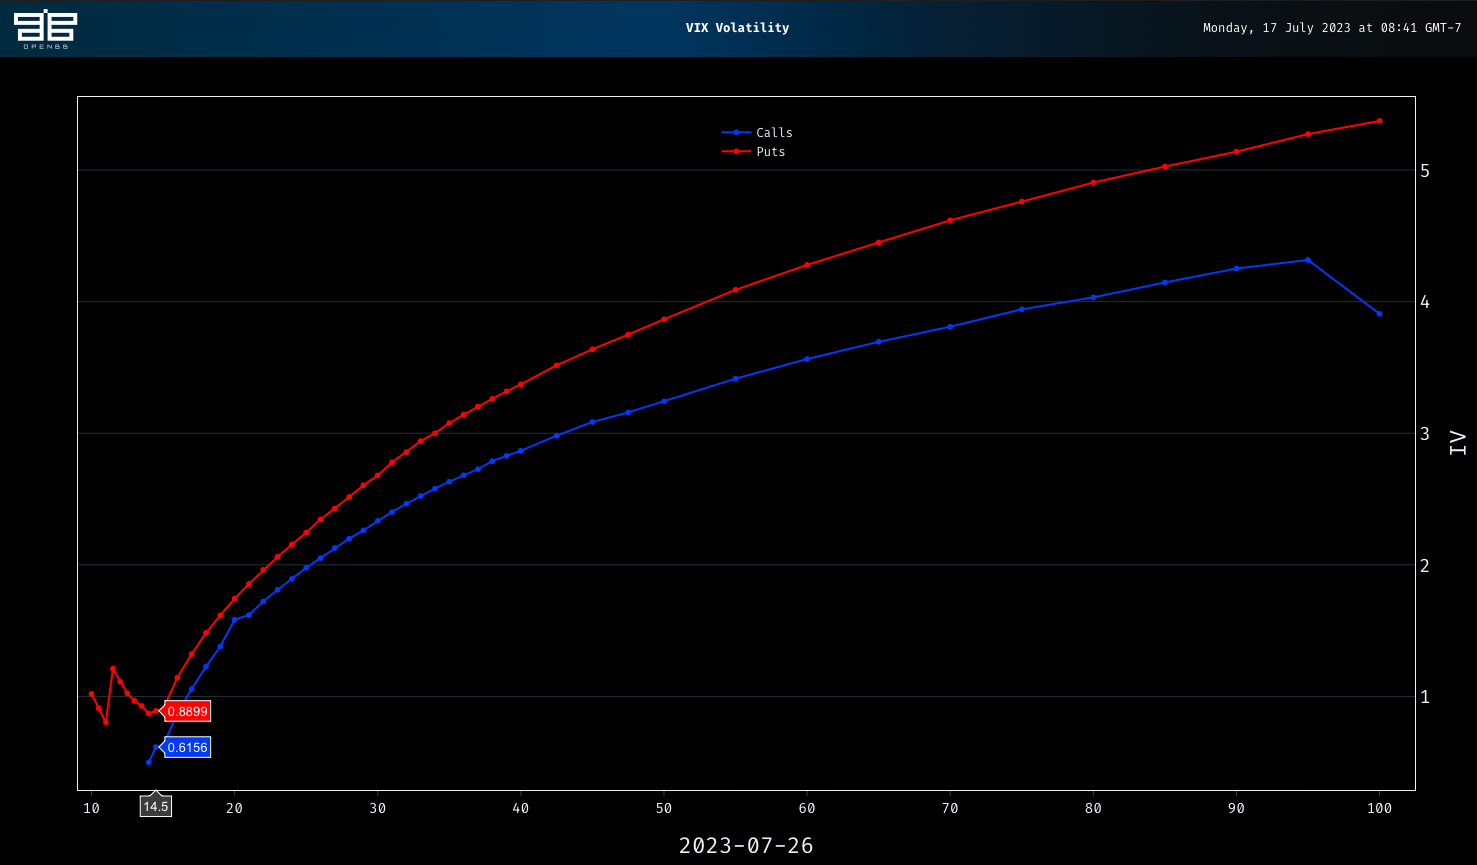
There are two types of views for volatility, smiles and surfaces.
|
|
|
|
#### `chart_volatility()`
|
|
|
|
As a default state, the put and call volatility smiles from the expiration in position 1, contained in the list `data.expirations[1]`, are displayed.
|
|
|
|
```python
|
|
data.chart_volatility()
|
|
```
|
|
|
|
|
|
|
|
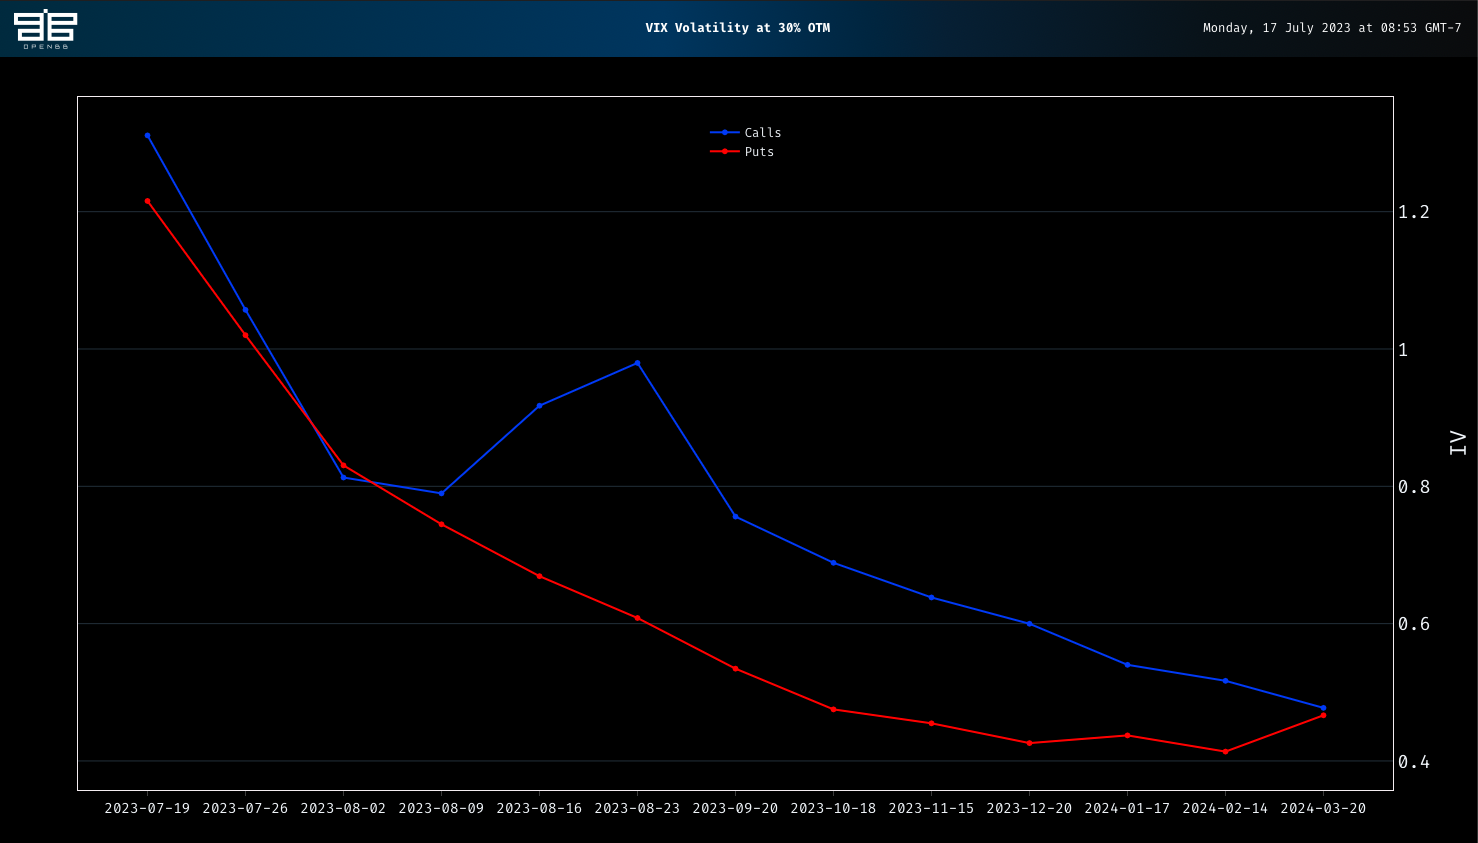
The implied volatility can also be visualized as the forward curve at a specific strike or % moneyness.
|
|
|
|
```python
|
|
data.chart_volatility(strike=20)
|
|
```
|
|
|
|

|
|
|
|
```python
|
|
data.chart_volatility(moneyness=30)
|
|
```
|
|
|
|
|
|
|
|
#### `chart_surface()`
|
|
|
|
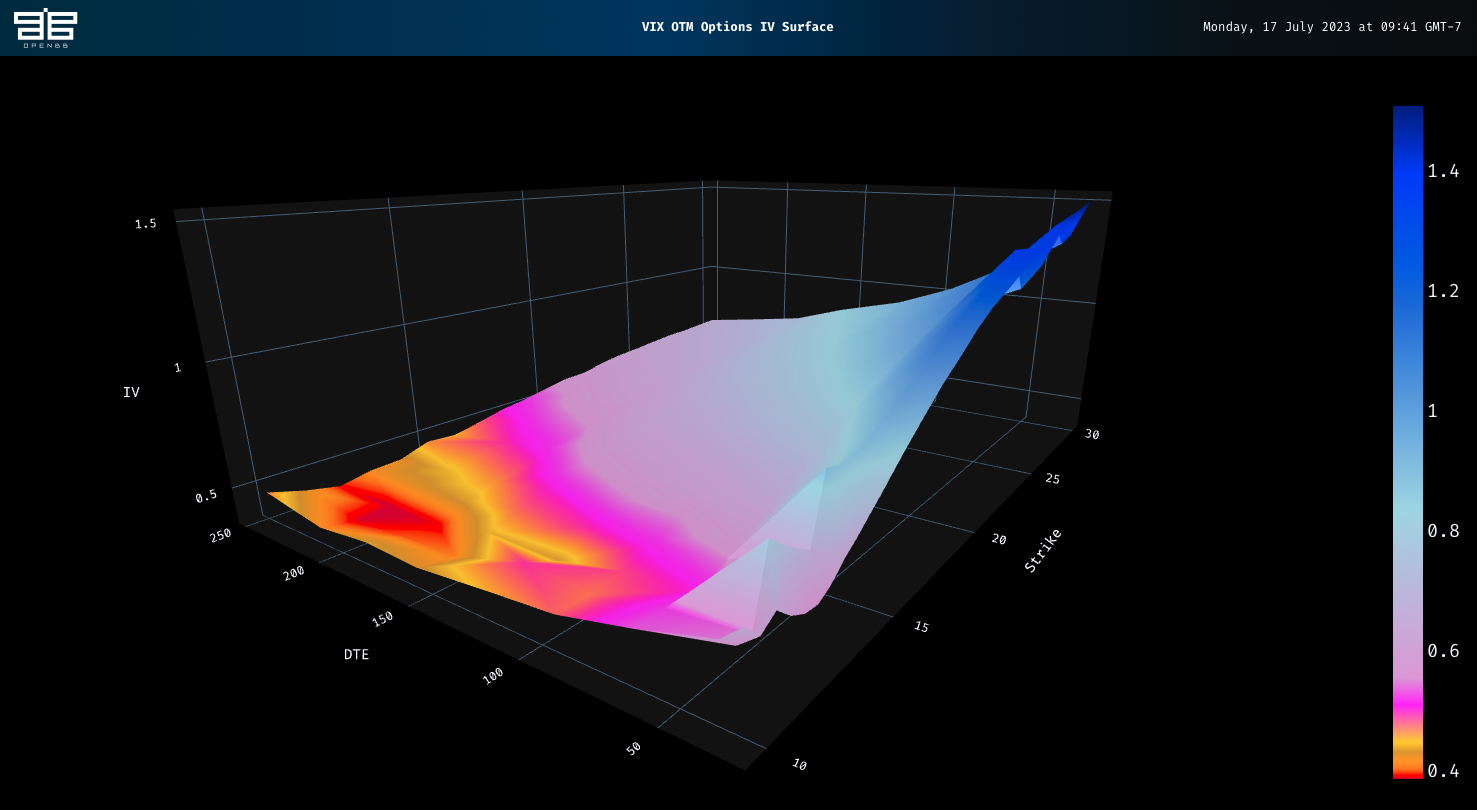
A portion, or the entire, volatility surface is presented as a 3-D chart. The data is arranged by types, selectable with the `option_type` parameter, choosing one of: `otm`, `itm`, `calls`, `puts`. The default state is `otm`. The X and Y axes can be narrowed to focus on a range of time and strike.
|
|
|
|
```python
|
|
data.chart_surface(dte_range = [30,300], strike_range = [10,30])
|
|
```
|
|
|
|
|
|
|
|
### Skew
|
|
|
|
Unlike volatility, there are both model and view components for the IV skew of the chain.
|
|
|
|
#### `get_skew()`
|
|
|
|
By default, this callable calculates the skew of every option. It can return either vertical or horizontal skew. Vertical skew can be narrowed to a specific expiry, and horizontal skew is determined by % OTM.
|
|
|
|
```python
|
|
data.get_skew(data.expirations[1]).query("12 <= `Strike` <= 15")
|
|
```
|
|
|
|
| | Expiration | Strike | Option Type | IV | ATM IV | Skew |
|
|
|----:|:-------------|---------:|:--------------|-------:|---------:|--------:|
|
|
| 116 | 2023-07-26 | 12 | put | 1.1136 | 0.9283 | 0.1853 |
|
|
| 117 | 2023-07-26 | 12.5 | put | 1.0246 | 0.9283 | 0.0963 |
|
|
| 118 | 2023-07-26 | 13 | put | 0.9666 | 0.9283 | 0.0383 |
|
|
| 119 | 2023-07-26 | 13.5 | put | 0.9283 | 0.9283 | 0 |
|
|
| 120 | 2023-07-26 | 14 | call | 0.4994 | 0.4994 | 0 |
|
|
| 121 | 2023-07-26 | 14 | put | 0.8702 | 0.9283 | -0.0581 |
|
|
| 122 | 2023-07-26 | 14.5 | call | 0.6156 | 0.4994 | 0.1162 |
|
|
| 123 | 2023-07-26 | 14.5 | put | 0.8899 | 0.9283 | -0.0384 |
|
|
| 124 | 2023-07-26 | 15 | call | 0.6245 | 0.4994 | 0.1251 |
|
|
| 125 | 2023-07-26 | 15 | put | 0.9002 | 0.9283 | -0.0281 |
|
|
|
|
```python
|
|
vix.get_skew(moneyness=20)
|
|
```
|
|
|
|
| expiration | Call Strike | Call IV | Call ATM IV | Call Skew | Put Strike | Put IV | Put ATM IV | Put Skew | ATM Skew | IV Skew |
|
|
|:-------------|--------------:|----------:|--------------:|------------:|-------------:|---------:|-------------:|-----------:|-----------:|----------:|
|
|
| 2023-07-19 | 16 | 1.0996 | 0.599 | 0.5006 | 10.5 | 1.0505 | 0.6328 | 0.4177 | -0.0338 | 0.0829 |
|
|
| 2023-07-26 | 16 | 0.8708 | 0.4994 | 0.3714 | 10.5 | 0.9101 | 0.9283 | -0.0182 | -0.4289 | 0.3896 |
|
|
| 2023-08-02 | 16 | 0.855 | 0.5026 | 0.3524 | 10.5 | 0.7438 | 0.6755 | 0.0683 | -0.1729 | 0.2841 |
|
|
| 2023-08-09 | 16 | 0.7861 | 0.4926 | 0.2935 | 10.5 | 0.6712 | 0.6575 | 0.0137 | -0.1649 | 0.2798 |
|
|
| 2023-08-16 | 16 | 0.8364 | 0.6284 | 0.208 | 10.5 | 0.6041 | 0.6117 | -0.0076 | 0.0167 | 0.2156 |
|
|
| 2023-08-23 | 16 | 0.9273 | 0.8918 | 0.0355 | 10.5 | 0.5492 | 0.6356 | -0.0864 | 0.2562 | 0.1219 |
|
|
| 2023-09-20 | 16 | 0.7023 | 0.5481 | 0.1542 | 10 | 0.5344 | 0.548 | -0.0136 | 0.0001 | 0.1678 |
|
|
| 2023-10-18 | 16 | 0.6447 | 0.5183 | 0.1264 | 10 | 0.4751 | 0.5178 | -0.0427 | 0.0005 | 0.1691 |
|
|
| 2023-11-15 | 16 | 0.6064 | 0.5069 | 0.0995 | 10 | 0.4548 | 0.4947 | -0.0399 | 0.0122 | 0.1394 |
|
|
| 2023-12-20 | 16 | 0.5716 | 0.4754 | 0.0962 | 10 | 0.426 | 0.4734 | -0.0474 | 0.002 | 0.1436 |
|
|
| 2024-01-17 | 16 | 0.5224 | 0.4248 | 0.0976 | 10 | 0.4372 | 0.4372 | 0 | -0.0124 | 0.0976 |
|
|
| 2024-02-14 | 16 | 0.494 | 0.4228 | 0.0712 | 10 | 0.4136 | 0.4258 | -0.0122 | -0.003 | 0.0834 |
|
|
| 2024-03-20 | 16 | 0.4533 | 0.4008 | 0.0525 | 10 | 0.4665 | 0.4162 | 0.0503 | -0.0154 | 0.0022 |
|
|
|
|
#### chart_skew()
|
|
|
|
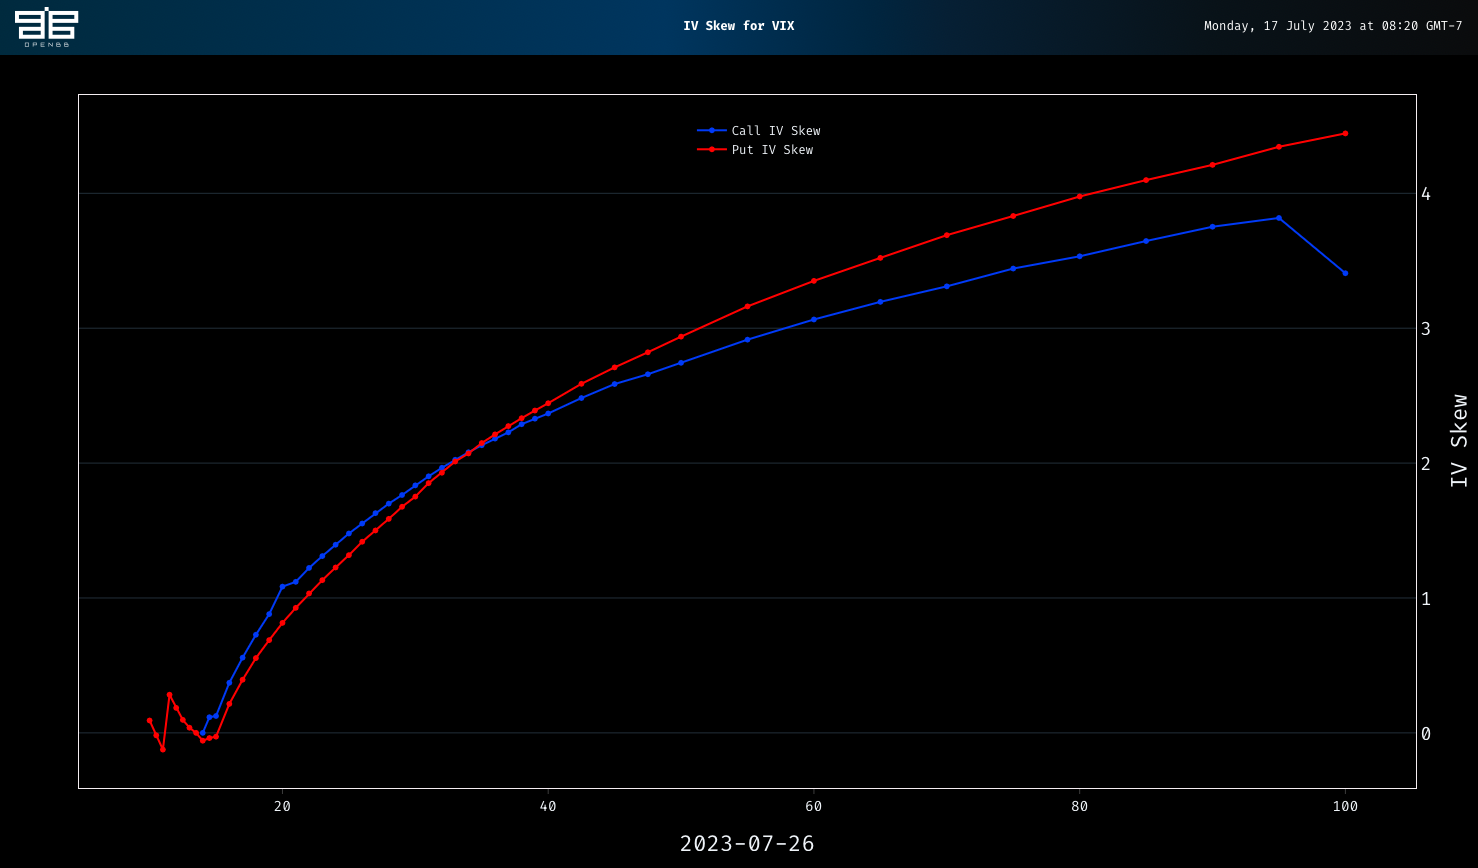
As a default state, the put and call skew smiles from the expiration in position 1, contained in the list `data.expirations[1]`, are displayed.
|
|
|
|
`data.chart_skew()`
|
|
|
|
|
|
|
|
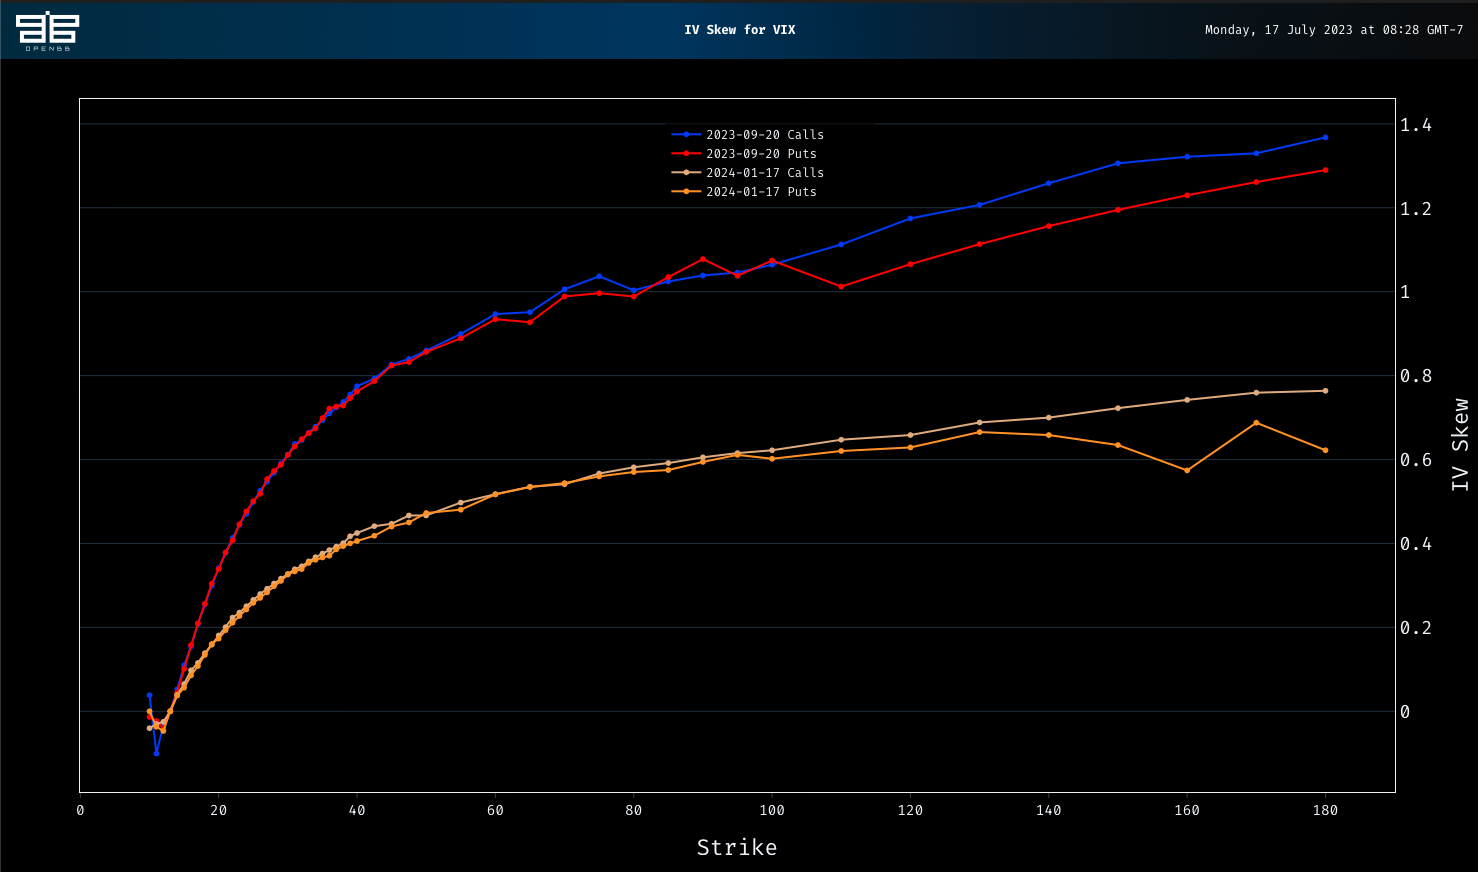
Multiple expirations can be displayed by entering a list to the `expirations` parameter.
|
|
|
|
`data.chart_skew(expirations=[data.expirations[6],data.expirations[10]])`
|
|
|
|
|
|
|
|
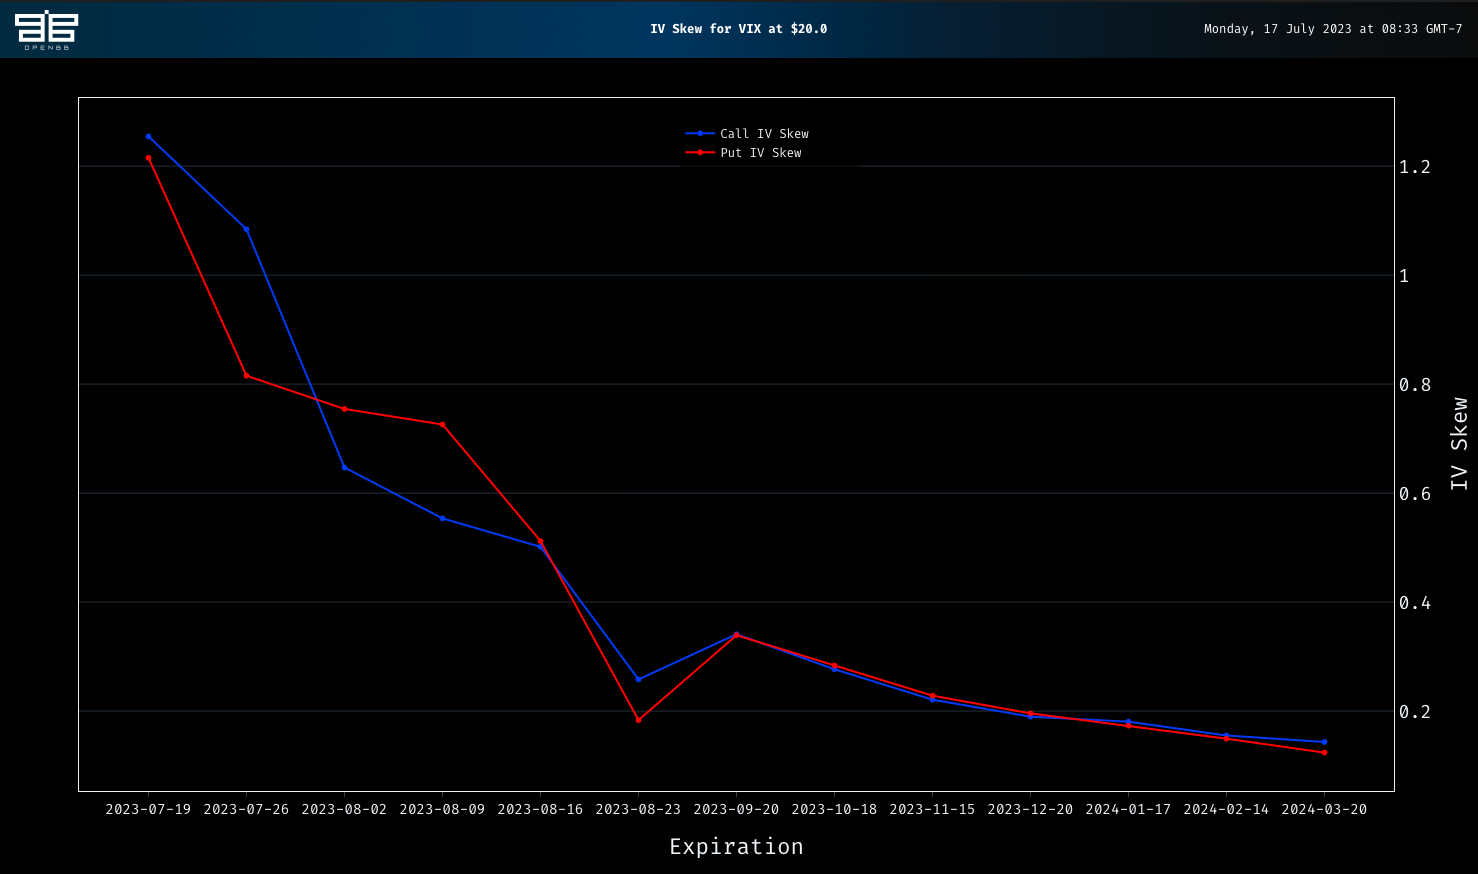
The forward curve is also callable by strike.
|
|
|
|
`data.chart_skew(strike = 20)`
|
|
|
|
|